
3% Withholding Tax on Spanish Property Sales by Non-Residents | Guide
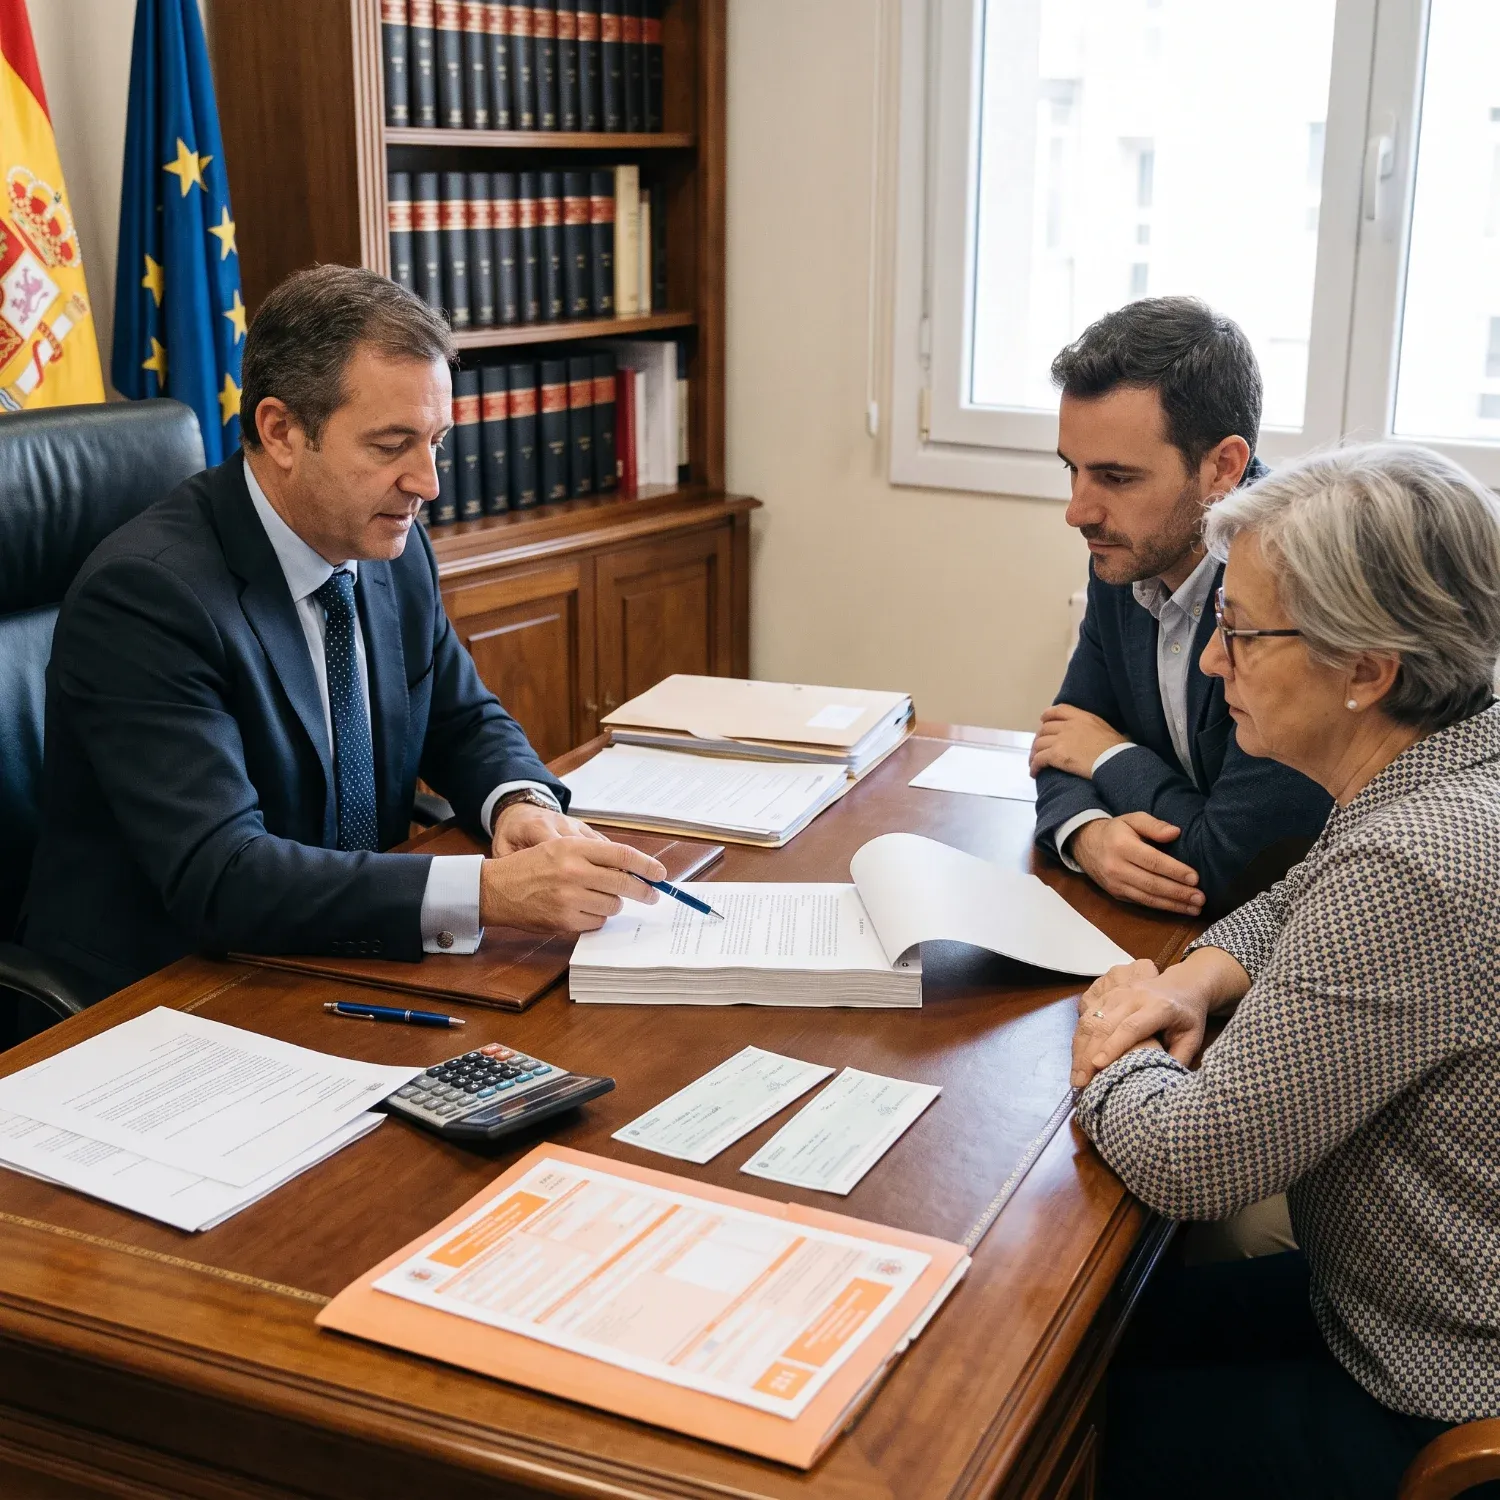
The buyer’s tax toll: why purchasing property from a non-resident requires withholding 3% of the price
The widespread belief that property sale taxes fall solely on the seller collapses under Spanish tax law: if the vendor is non-resident, the buyer becomes the legally mandated tax collector under threat of direct liability.
In any standard real estate transaction, the expectations of the parties seem straightforward: the buyer pays the agreed purchase price alongside transmission taxes, while the seller collects the remaining funds to settle their own capital gains tax. However, when the transferor is not a tax resident in Spain—whether a foreign national or a Spanish citizen formally relocated abroad—the legal rules change entirely.
Spanish tax authorities place little faith in non-residents voluntarily settling their Non-Resident Income Tax (Impuesto sobre la Renta de No Residentes or IRNR) once sale proceeds have crossed borders into an international bank account. Consequently, the law shifts this burden directly onto the transaction: it appoints the purchaser as an obligatory withholding agent, legally bound to deduct and remit exactly 3% of the total purchase price directly to the Spanish Tax Agency.
The trap of ignorance: the buyer as subsidiary liable party
The greatest hazard for an incoming buyer lies in misjudging this 3% retention as an optional arrangement or an internal commercial matter. It is neither. Article 25 of the Non-Resident Income Tax Act (Real Decreto Legislativo 5/2004) mandates that the purchaser must withhold this amount at the precise moment the public deed of sale (escritura pública) is executed before the notary.
Should the buyer—whether due to poor legal counsel or contractual oversight—remit 100% of the purchase price directly to the non-resident seller, the Spanish Tax Agency (Agencia Tributaria) will not pursue an arduous cross-border collection claim in the seller’s country of origin. Instead, the tax office moves swiftly against the buyer.
Under statutory lien provisions, the acquired property remains automatically encumbered as collateral for the unpaid withholding tax, statutory interest, and applicable penalties. Overnight, the purchaser faces an inherited tax liability that should have been subtracted from the purchase price, becoming the de facto payer of the vendor’s tax bill.
The formal procedure: Form 211 and statutory deadlines
The withholding mechanism does not conclude at the notary’s table with the delivery of a bank draft for the remaining 97%. Spanish regulations impose a strict compliance procedure subject to non-negotiable deadlines:
Remittance to the Public Treasury: The purchaser has an unextendable deadline of one month from the date of the notarial deed to file and pay the retained sum using Form 211 (Modelo 211).
Delivery of payment proof: Once processed, the buyer must furnish the non-resident seller with an official copy of Form 211, validated by the receiving financial institution or the Tax Agency’s electronic portal.
The seller’s final assessment: Armed with Form 211, the vendor has three months to submit Form 210 (Modelo 210), calculating their actual capital gain. If their actual tax liability is lower than the 3% withheld, they may claim a refund of the excess from the Spanish Treasury; if the gain yields a higher tax obligation, they must remit the difference.
Any administrative flaw in this chain—such as misidentifying tax identification numbers (NIE/NIF) or missing filing windows—leaves the buyer directly exposed to tax surcharges and formal notifications.
The notarial and banking filter: preventive drafting from the preliminary agreement
While the executing notary will warn the parties and insert mandatory tax warnings within the title deed, waiting until the signing date to address the retention frequently sparks friction or outright derailment. Many non-resident sellers, unfamiliar with Spanish conveyancing law, mistakenly perceive the 3% retention as an arbitrary discount or an unexpected price cut.
Prudence requires addressing this requirement in the very first binding contract. The preliminary deposit agreement (contrato de arras) must clearly establish:
The vendor’s non-resident tax status (or formal refutation via a valid tax residency certificate issued by the Spanish Tax Agency).
The buyer’s non-negotiable statutory duty to withhold 3% of the agreed purchase price at the notarial closing.
A clear breakdown of payment instruments, providing for separate certified bank drafts: one for the 97% balance payable to the seller, and another for the 3% reserved to settle Form 211.
A necessary reflection for real estate professionals
In an international property market, fiscal residency is never a trivial administrative detail; it is a structural pillar of the financial transaction. Leaving the 3% withholding to chance or dismissing it as an afterthought jeopardizes the buyer’s title security and professional credibility.
Securing certified tax residency proof well in advance, structuring split payment drafts prior to completion, and managing Form 211 with technical precision represent the only dependable defense against an investment saddled with inherited tax debt.